Products • Risk Analytics

Monitor Live Exposure. Catch Early Stress. See Risk Before It Reaches Your Numbers.

Live portfolio intelligence and early-warning signals, built on the same data your lending runs on. No manual CSV exports, no reconciliation disputes, and no stale month-end packs.

  • Live multi-dimensional portfolio & vintage dashboards
  • AI-driven Early Warning Signals (EWS) & roll-rate tracking
  • Closed-loop underwriting feedback & stress testing

Built to move
lending forward.

Real-Time Portfolio Visibility Over Hindsight Reporting

By the time a traditional month-end risk pack lands, the risk has already moved. Replace weeks-late static reports with continuously updating dashboards that track exposure, delinquency (SMA-0/1/2), and NPA movements in real time across products, regions, branches, and cohorts.

One Single Source of Truth Across Risk, Credit & Finance

Stop wasting leadership bandwidth when Risk, Credit, and Finance pull numbers from different systems and argue over whose spreadsheet is right. Run every portfolio view, expected credit loss (ECL) calculation, and board pack directly on live origination, servicing, and collection data.

Granular Cohort & Segment Drill-Downs That Unmask Hidden Stress

Warning signs hide inside healthy-looking portfolio averages. Automatically isolate stressed micro-segments, underperforming DSAs, slipping branches, or deteriorating co-lending partners—and drill down from macro portfolio trends to an individual loan file in three clicks.

30–45 DaysEarlier Stress DetectionProactive Early Warning Signals (EWS) & cohort anomaly alerts before bucket roll-forwards
Under 1 HourRisk Pack PrepAutomated board & committee packs generated from live data (down from 5–7 days of manual prep)
15–20%Lower Early DelinquencyClosed-loop BRE policy calibration & pre-delinquency pushes straight to Collections
100%Unified Risk TruthZero reconciliation gaps across Risk, Credit, Finance & Audit on one shared data model

See risk intelligence move
from live data to decisive action.

  1. 01

    Connect

    Loan origination, repayment, collections, co-lending, and bureau refresh data flow in continuously from Rewafin and your external systems.

  2. 02

    Monitor

    Live dashboards update automatically across every dimension—product, geography, branch, sourcing channel, partner, and disbursement vintage.

  3. 03

    Detect

    Rule-based triggers and machine-learning EWS models flag accounts, branches, and segments exhibiting early repayment stress or concentration breaches.

  4. 04

    Investigate

    Drill seamlessly from top-level portfolio KPIs down to a specific cohort, credit rule, underwriter queue, or individual borrower record in a few clicks.

  5. 05

    Act

    Tighten BRE approval rules in LOS, adjust exposure limits, or push stressed accounts directly into Collections queues—and measure the impact in real time.

AI that works.
Spot the pattern, not just the number.

Core Risk Analytics
capabilities.

Live Portfolio & Concentration Dashboards

Monitor exposure, delinquency, and prudential limits by any dimension.

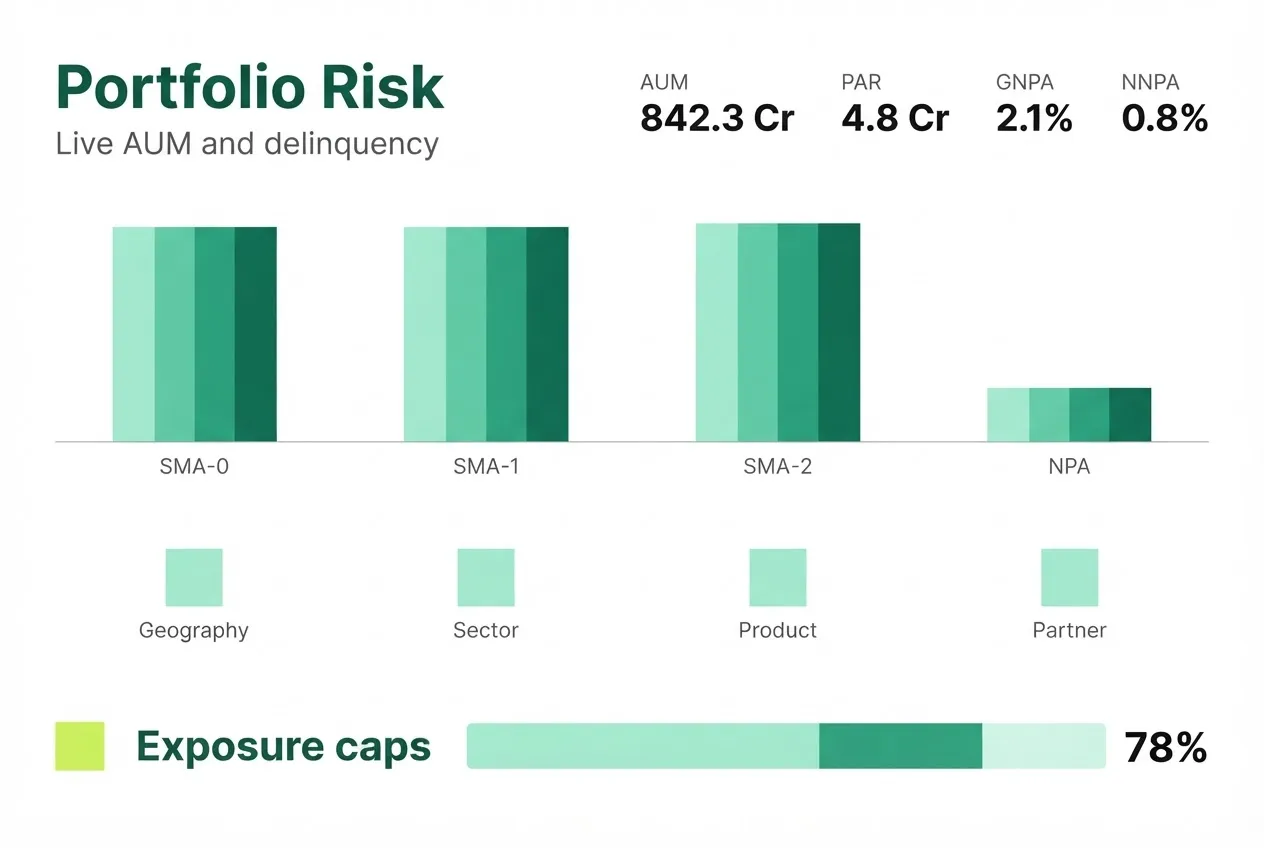
Track live AUM, PAR (Portfolio at Risk), SMA buckets, and GNPA/NNPA ratios alongside real-time concentration guardrails across geography, sector, product, partner, and borrower groups.

  • Multi-dimensional PAR, SMA-0/1/2 & NPA tracking
  • Geography, industry, product & partner exposure caps
  • Single and group borrower concentration alerts
  • Role-based views for branch, regional & HO teams

Vintage, Cohort & Roll-Rate Analytics

See how every month's disbursements perform over their entire lifecycle.

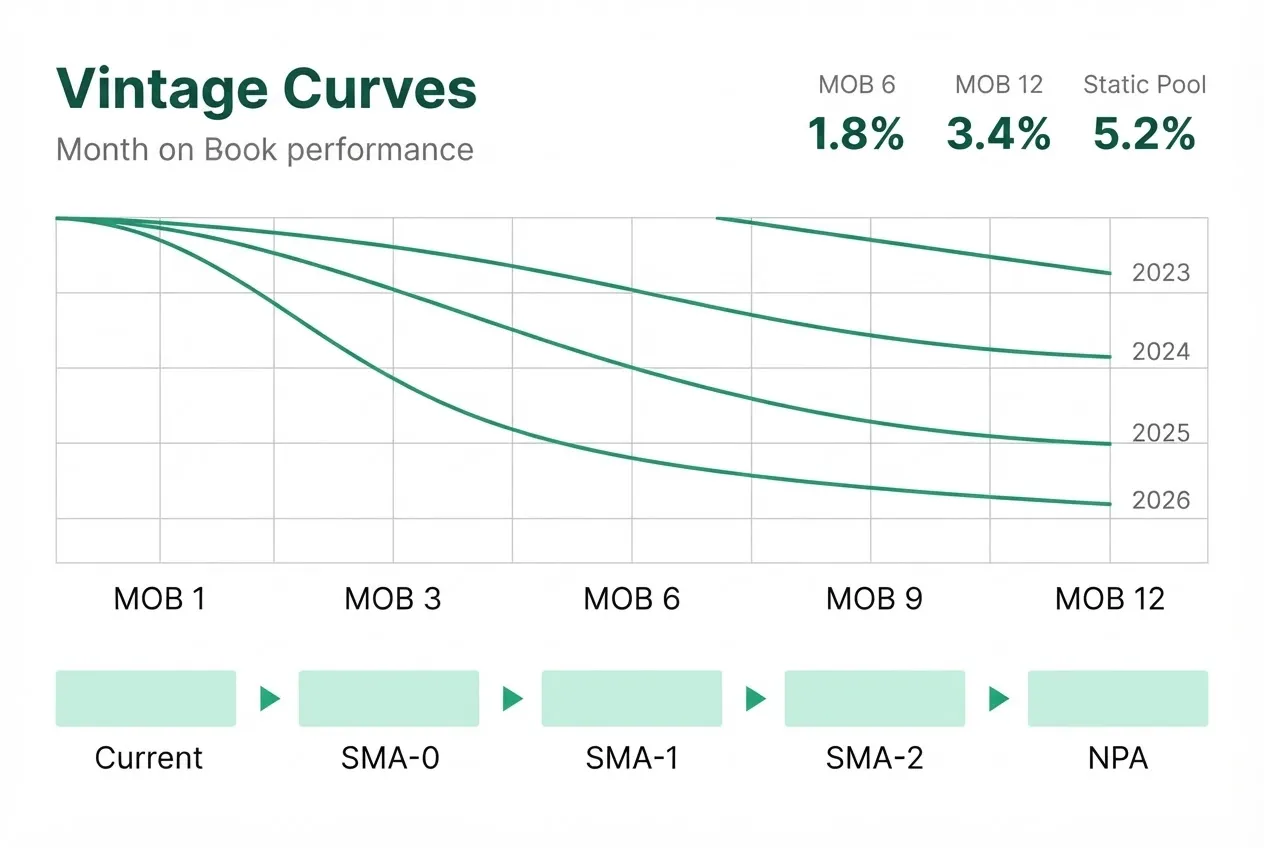
Analyze Month-on-Book (MOB) vintage curves, static pool losses, and bucket-to-bucket roll rates to identify exactly when and where accounts begin slipping into delinquency.

  • Month-on-Book (MOB) vintage & static pool curves
  • Net flow & bucket-to-bucket roll-rate matrices
  • Bounce-to-cure & collection efficiency tracking
  • Early mortality (FPD / SPD / TPD) cohort heatmaps

Early Warning System (EWS) & Action Triggers

Catch stressed accounts and segments weeks before default.

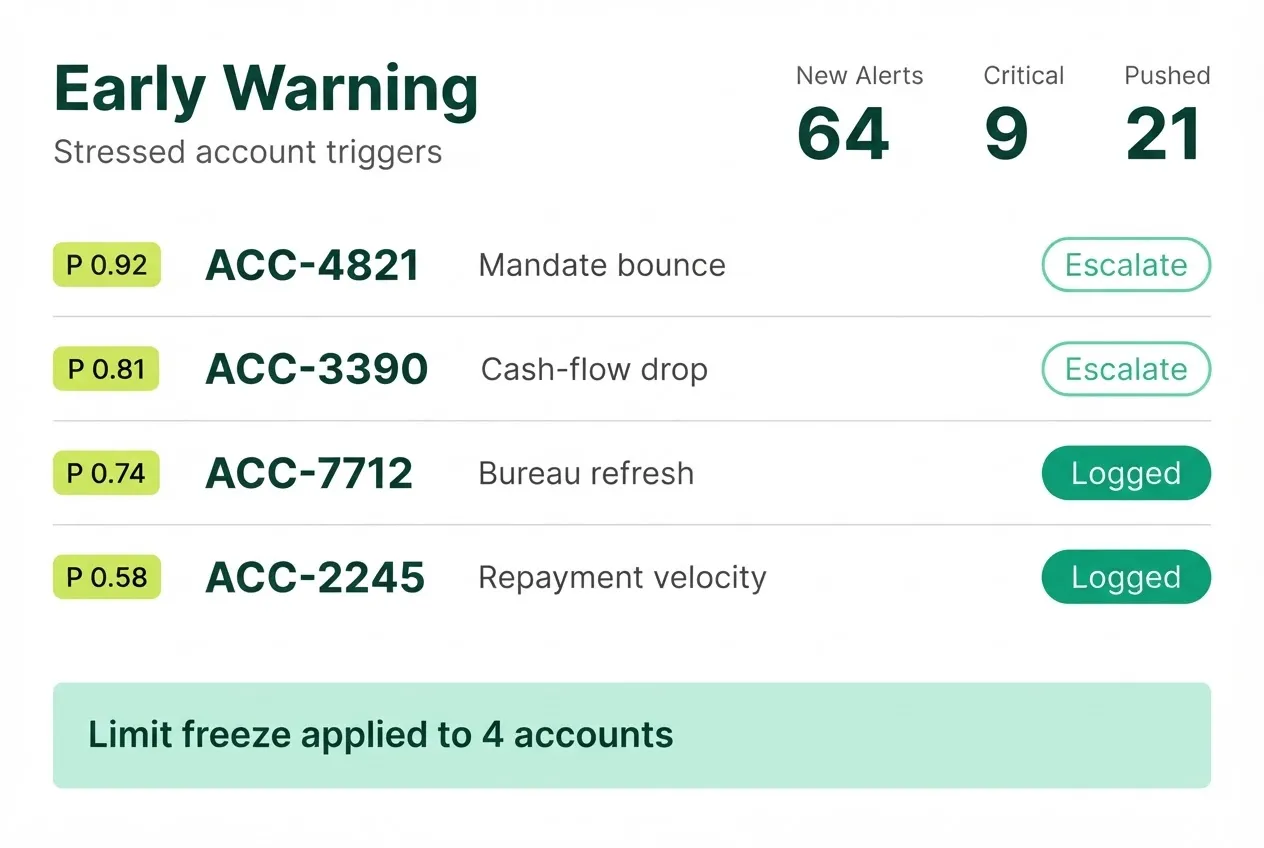
Combine internal repayment velocity, mandate bounces, cash-flow drops, and periodic bureau scrubs to trigger automated risk alerts and preemptive intervention workflows.

  • Account, branch, DSA & partner EWS triggers
  • Periodic bureau refresh & external delinquency tracking
  • Automated push of stressed accounts to Collections
  • Real-time limit freeze & top-up block triggers

Underwriting Loop & Credit Policy Analytics

Close the loop between origination policy and portfolio outcomes.

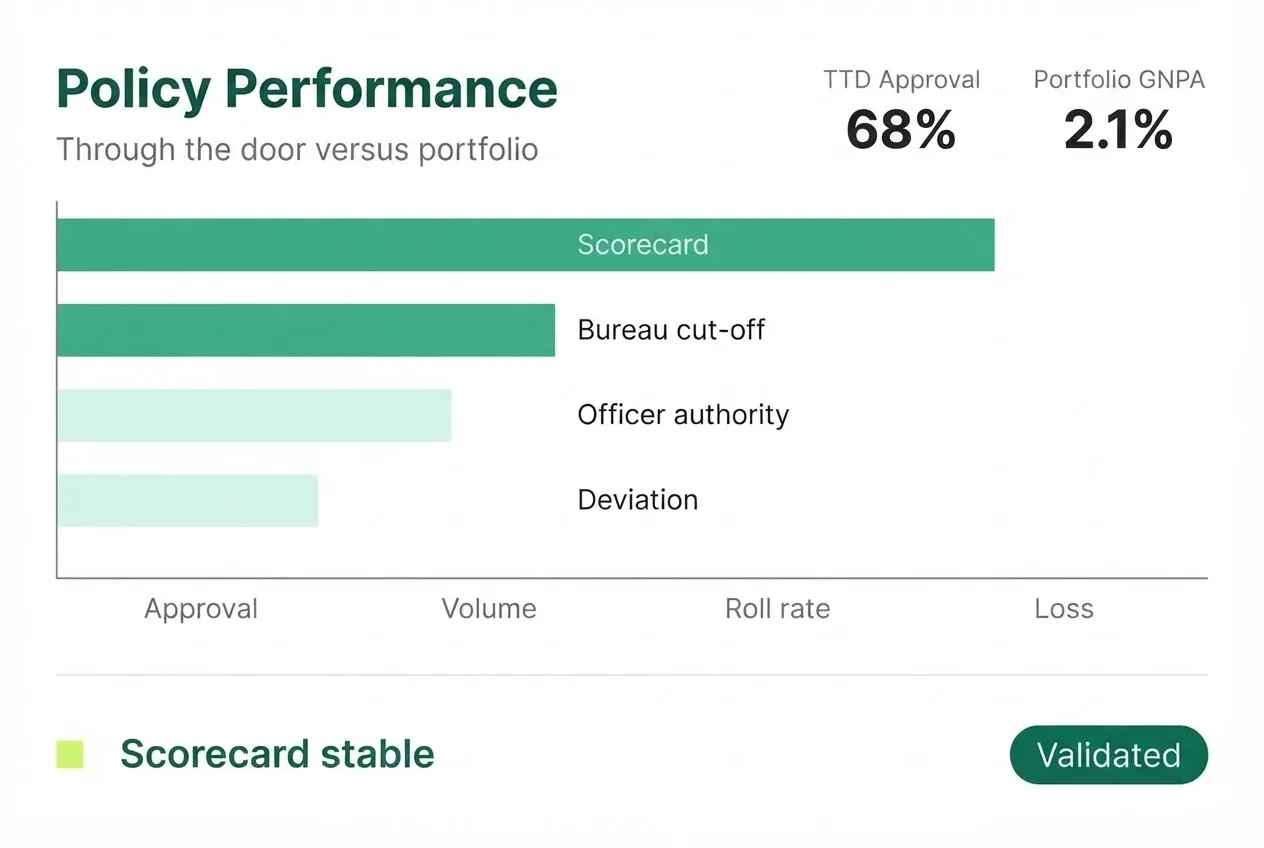
Evaluate the real-world performance of every underwriting scorecard, bureau cut-off, credit officer authority, and policy deviation to continuously sharpen your LOS rule engine.

  • Through-the-door (TTD) vs. portfolio quality tracking
  • Scorecard Gini, KS & rank-ordering validation
  • Credit deviation & exception performance audit
  • Channel, DSA & connector quality scorecards

Stress Testing, Provisioning & Board Reporting

Deliver audit-ready provisioning and scheduled leadership packs automatically.

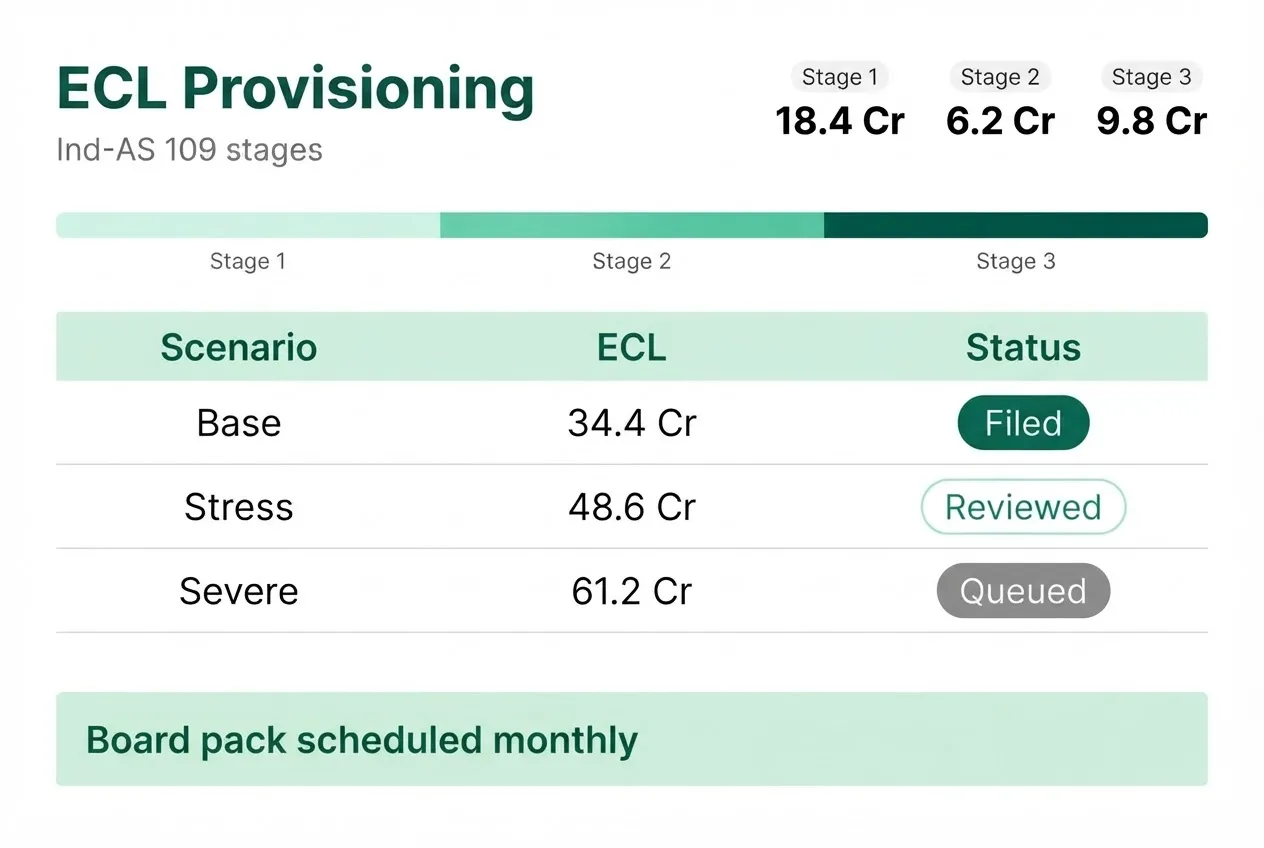
Run sensitivity simulations on your loan book, calculate RBI IRACP and Ind-AS 109 Expected Credit Loss (ECL) provisions, and distribute scheduled risk packs to leadership and the board.

  • What-if scenario & macro sensitivity modeling
  • Ind-AS 109 (Stage 1/2/3 ECL) & IRACP provisioning views
  • Automated monthly Risk Committee & Board packs
  • Custom report builder with scheduled delivery

Calibrated risk intelligence
for your lending institution.

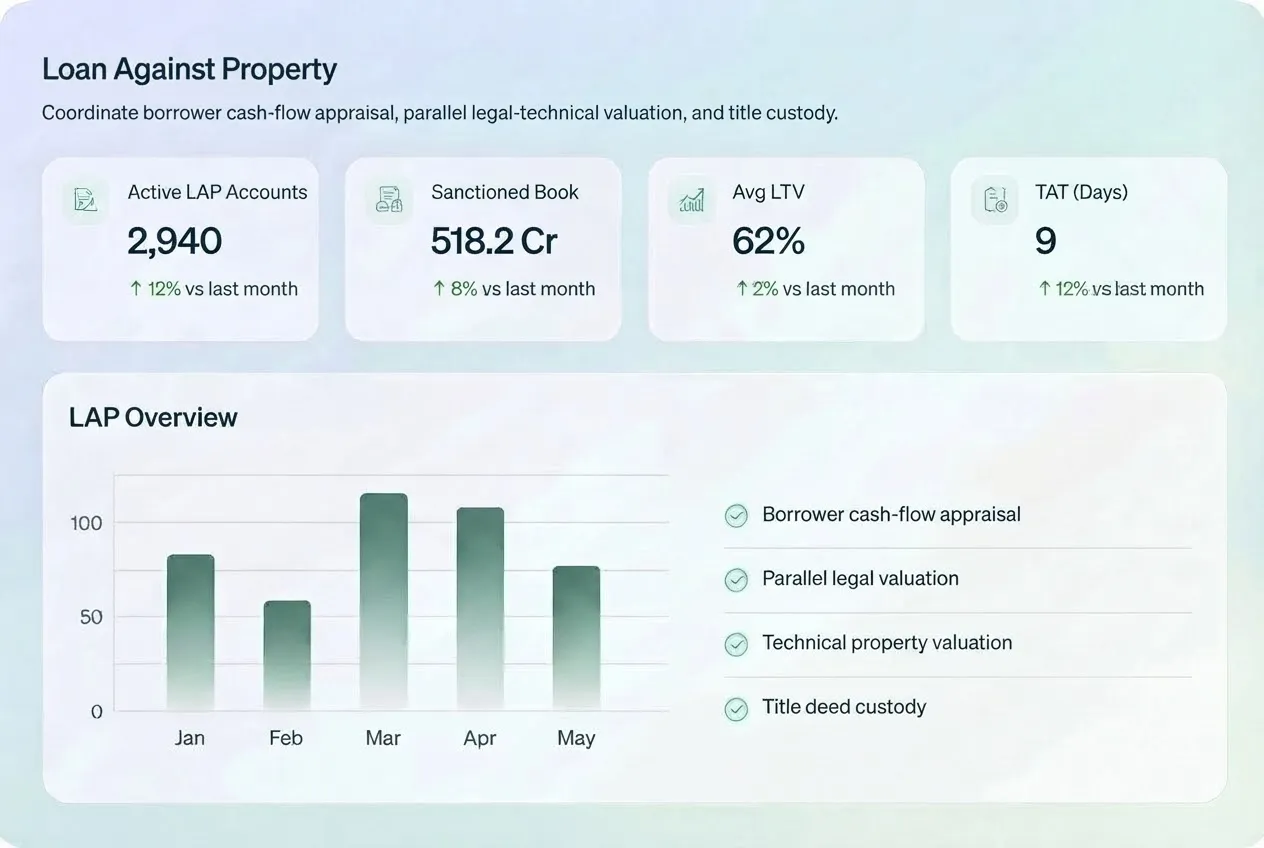
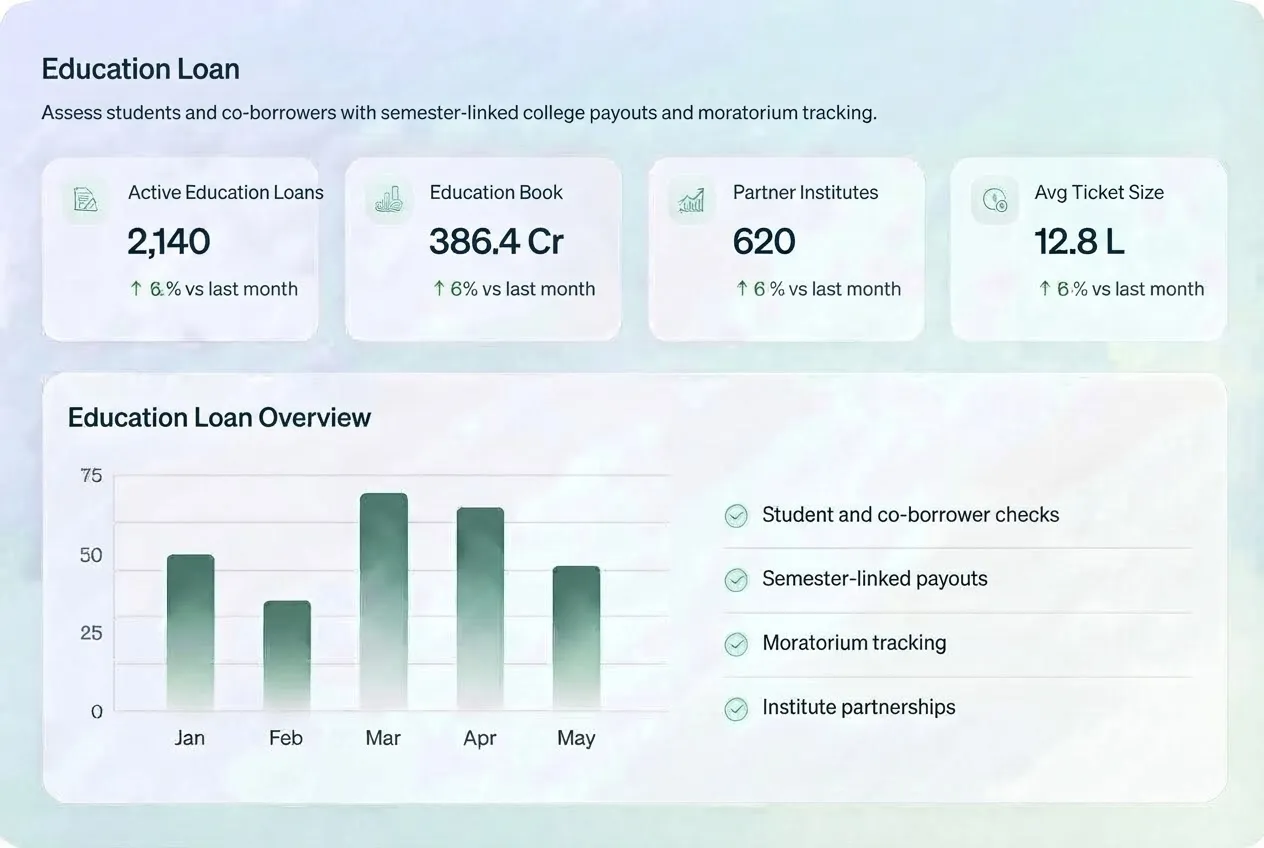
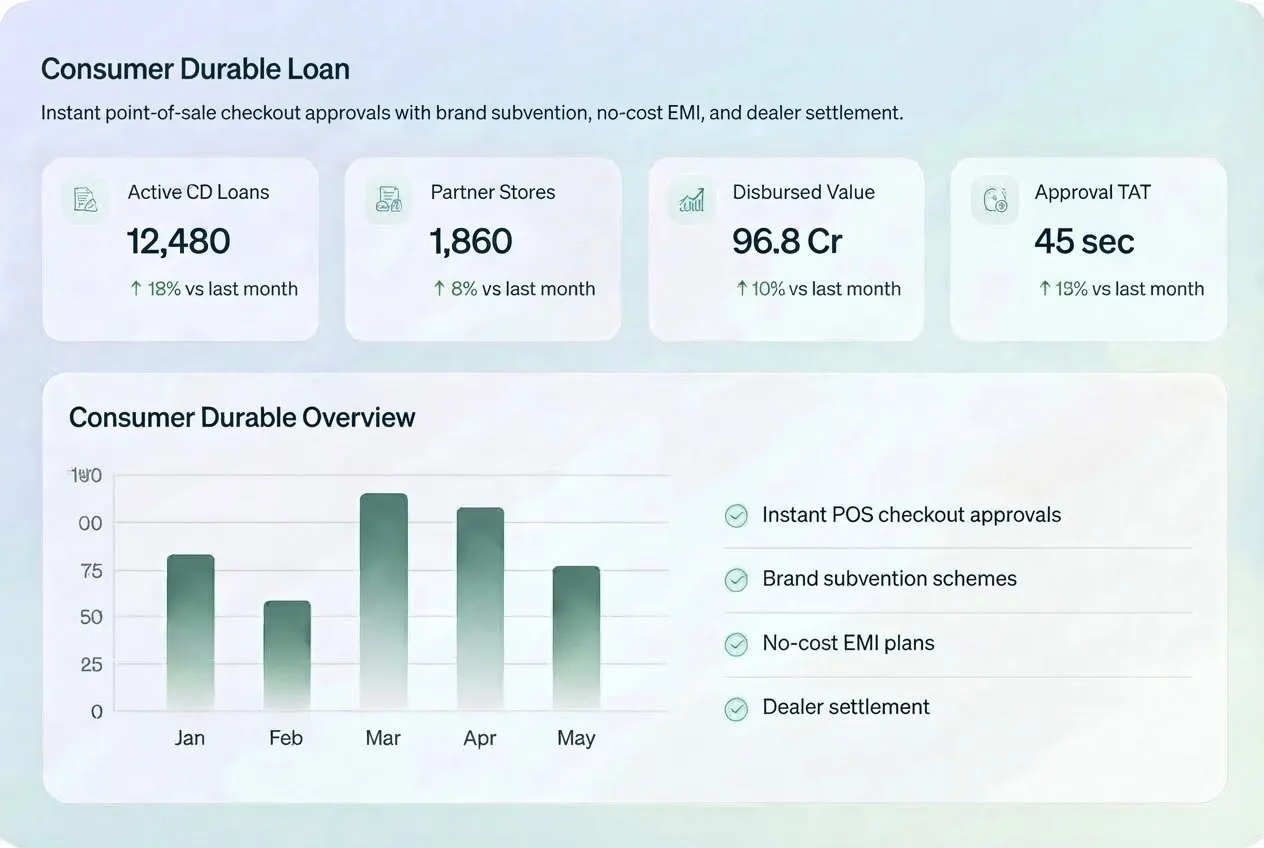
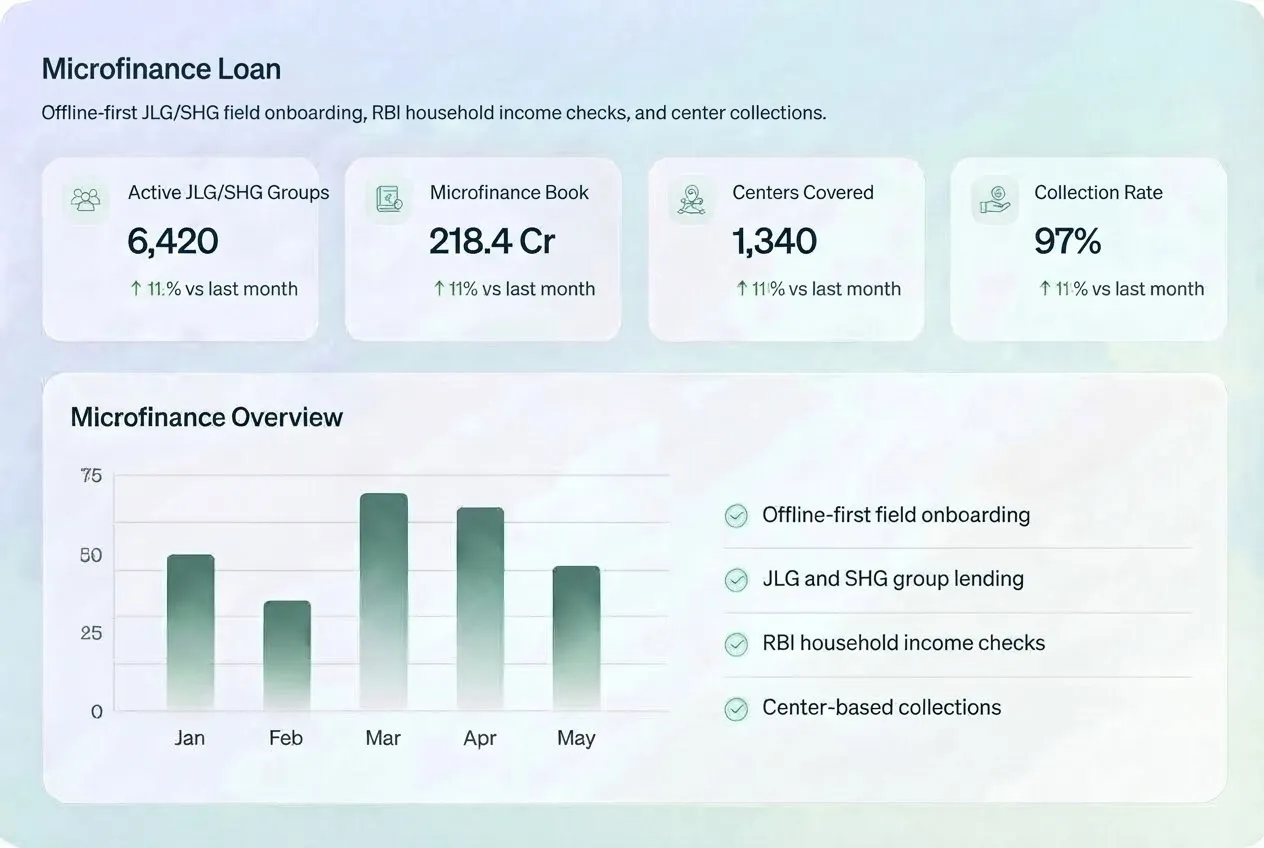
From high-velocity unsecured retail books to long-tenure housing and rural microfinance portfolios, Rewafin adapts risk metrics and early warnings to your regulatory and asset reality.

One platform.
Every lending journey.

Connects to the lending and data rails you already run on

Built natively on the Rewafin data core, with open APIs and connectors to ingest data from external LOS, LMS, Core Banking, bureaus, and enterprise data warehouses.

Native Rewafin Suite Continuity

  • LOSOrigination approval decisions, bureau scores, and policy deviations link directly to long-term loan performance.
  • LMSLive repayment schedules, DPD counters, bounces, and ledger balances stream in continuously with zero CSV exports.
  • Collections & RecoveryEarly-warning accounts route straight into prioritized collection queues; roll rates and PTP outcomes feed back in real time.
  • Co-LendingTrack delinquency, vintage curves, and exposure limits by co-lending partner, CLM model, and programme.

External Bureaus, Data Warehouses & BI Stack

4-Bureau Portfolio Scrubs & Alerts (TransUnion CIBIL, CRIF High Mark, Experian, Equifax)Account Aggregator (AA) & GSTN Cash-Flow SignalsExternal CBS, LOS & LMS API/Batch ConnectorsEnterprise Data Warehouses & BI Tools (Snowflake, BigQuery, PowerBI, Tableau)
Frequently
asked questions

Still unsure? Our lending specialists are happy to walk through the specifics for your institution.

Talk to our team

Yes. It connects seamlessly to your existing third-party LOS, LMS, Core Banking System, and data warehouse through REST APIs and scheduled automated imports.

See where your portfolio is heading, not where it was.

In 30 minutes, we'll show your team a live view of portfolio risk, vintage performance, and early-warning signals built on your own data model.